10 Monthly Bills Worth Reviewing Before You Retire
Retirement planning often makes us think about big numbers: the size of a 401(k), pension income, Social Security, investment returns, or whether $1 million will be enough.
But sometimes the easiest place to improve retirement security is much closer to home.
It is sitting inside your monthly bills.
A $25 subscription, a $90 insurance add-on, or a $150 service you barely use may not feel important on its own. But once retirement income becomes more fixed, recurring expenses can quietly consume thousands of dollars every year.
That is why reviewing monthly bills before retirement can be one of the simplest forms of personal finance after 50.
The goal is not to remove every pleasure from life. It is to decide which expenses still deserve a permanent place in your budget.
Here are 10 monthly bills worth reviewing before you retire.
1. Your Mortgage or Rent
Housing is often the largest monthly expense in retirement.
If your mortgage payment is $1,800 per month, that represents $21,600 every year before property taxes, insurance, repairs, or utilities.
A few years before retirement, ask yourself whether your current home still fits your future lifestyle.
Do you need the same amount of space?
Will property taxes continue rising?
Could maintenance become difficult later?
Would moving to a smaller home significantly lower your monthly expenses?
Downsizing is not automatically the right choice, but housing deserves careful attention because reducing this one bill can sometimes save more than dozens of smaller budget cuts combined.
2. Car Payments
A new vehicle may feel affordable while you are earning a full salary.
A $650 monthly car payment feels very different when your retirement income drops.
That payment alone equals:
$7,800 per year.
Add insurance, fuel, maintenance, registration, and repairs, and transportation can become one of your largest retirement expenses.
If possible, consider whether keeping a reliable paid-off vehicle longer could help reduce your required retirement income.
You do not necessarily need the newest car.
You need transportation that fits comfortably inside your retirement budget.
3. Auto Insurance
Insurance premiums can quietly increase over time.
Many people renew automatically without reviewing:
- deductibles,
- mileage assumptions,
- optional coverage,
- multiple-car discounts,
- bundling opportunities,
- or whether an older vehicle still needs the same coverage.
Before retirement, ask for updated quotes and review the policy line by line.
Saving even $50 per month equals $600 per year.
Over ten retirement years, that is $6,000 before considering what those savings could have earned if invested.
4. Homeowners Insurance
Your homeowners insurance deserves the same attention.
You want adequate protection, but you also want to understand exactly what you are paying for.
Review your deductible, replacement-cost assumptions, optional riders, and bundled discounts.
You may also discover that the value of certain belongings has changed over the years.
Insurance is not an area where the cheapest policy is automatically best.
The goal is to avoid paying for unnecessary extras while maintaining coverage that protects the financial life you have spent decades building.
5. Cable and Streaming Services
This category has become surprisingly expensive.
One streaming service might cost only $15.
But perhaps you have:
Netflix: $20
Hulu: $18
Disney+: $16
Sports package: $25
Music service: $12
Cable television: $120
Suddenly entertainment subscriptions can exceed $200 per month.
That is more than $2,400 annually.
The easiest approach is not necessarily canceling everything.
Instead, ask:
“Do I actually use this every month?”
You might rotate streaming services instead of keeping six subscriptions active all year.
6. Cell Phone Plans
Many households stay with the same mobile provider for years without reviewing their plan.
That can mean paying for unlimited data you rarely use, device insurance on older phones, unnecessary lines, or expensive upgrades.
A couple paying $180 per month spends $2,160 every year on mobile service.
If another suitable plan costs $110, the annual difference is $840.
That is meaningful money in retirement.
Before changing providers, however, compare coverage, fees, device payments, and contract terms carefully.
A cheaper plan is not useful if it does not work reliably where you live.
7. Internet Service
Internet service often begins with a promotional price and slowly increases.
Many people simply accept the new bill.
Before retirement, review what speed you actually need.
If two retired adults mainly browse the web, watch streaming television, and video-call family, they may not need the most expensive premium package available.
Call your provider.
Ask about current plans.
Check competitor pricing.
And remove rented equipment you no longer need.
A small negotiation can sometimes produce surprisingly large annual savings.
8. Credit Card Interest
This may be the most important monthly bill on the entire list.
High-interest credit-card debt can be extremely damaging during retirement.
Imagine carrying a $10,000 balance at a high interest rate.
A significant portion of every payment may go toward interest rather than reducing the original debt.
That is money leaving your retirement budget without improving your lifestyle.
If you are approaching retirement with credit-card balances, creating a realistic payoff strategy can be extremely valuable.
For many households, eliminating expensive debt provides more immediate financial relief than trying to squeeze a slightly higher return from investments.
9. Gym Memberships and Clubs
Some memberships are absolutely worth keeping.
If your gym keeps you healthy, socially connected, and active, it may be one of the best expenses in your budget.
But many people continue paying memberships they rarely use.
Perhaps you joined a premium gym years ago but now exercise at home.
Maybe you belong to several professional organizations that were important during your career but will no longer matter after retirement.
Review every recurring membership.
The question is not:
“Is this expensive?”
The better question is:
“Does this still improve my life enough to justify paying for it every month?”
That mindset creates a smarter retirement budget without making retirement feel restrictive.
10. Subscription Services You Forgot About
This is where modern budgets can become surprisingly messy.
Subscriptions may include:
- cloud storage,
- software,
- news sites,
- apps,
- meal services,
- premium delivery memberships,
- digital magazines,
- photo storage,
- security services,
- hobby platforms.
Many cost only $5 to $20 per month.
That is precisely why they are easy to ignore.
Review several months of credit-card and bank statements and highlight every recurring charge.
You may discover subscriptions you had completely forgotten about.
Canceling five unused $15 services saves $75 monthly.
That equals $900 per year.
Why Monthly Expenses Matter So Much in Retirement
Suppose you reduce recurring expenses by $500 per month before retiring.
That creates:
$6,000 of annual savings.
Using a simple 4% retirement-withdrawal illustration, generating an additional $6,000 annually from investments could require approximately:
$150,000 of portfolio assets.
That does not mean cutting $500 in expenses is literally identical to adding $150,000 to your retirement account.
Taxes, investment returns, inflation, and withdrawal strategies matter.
But it illustrates something powerful:
Lower spending can significantly reduce the amount of investment income your lifestyle requires.
Sometimes the easiest way to make retirement savings last longer is not earning more.
It is needing less.
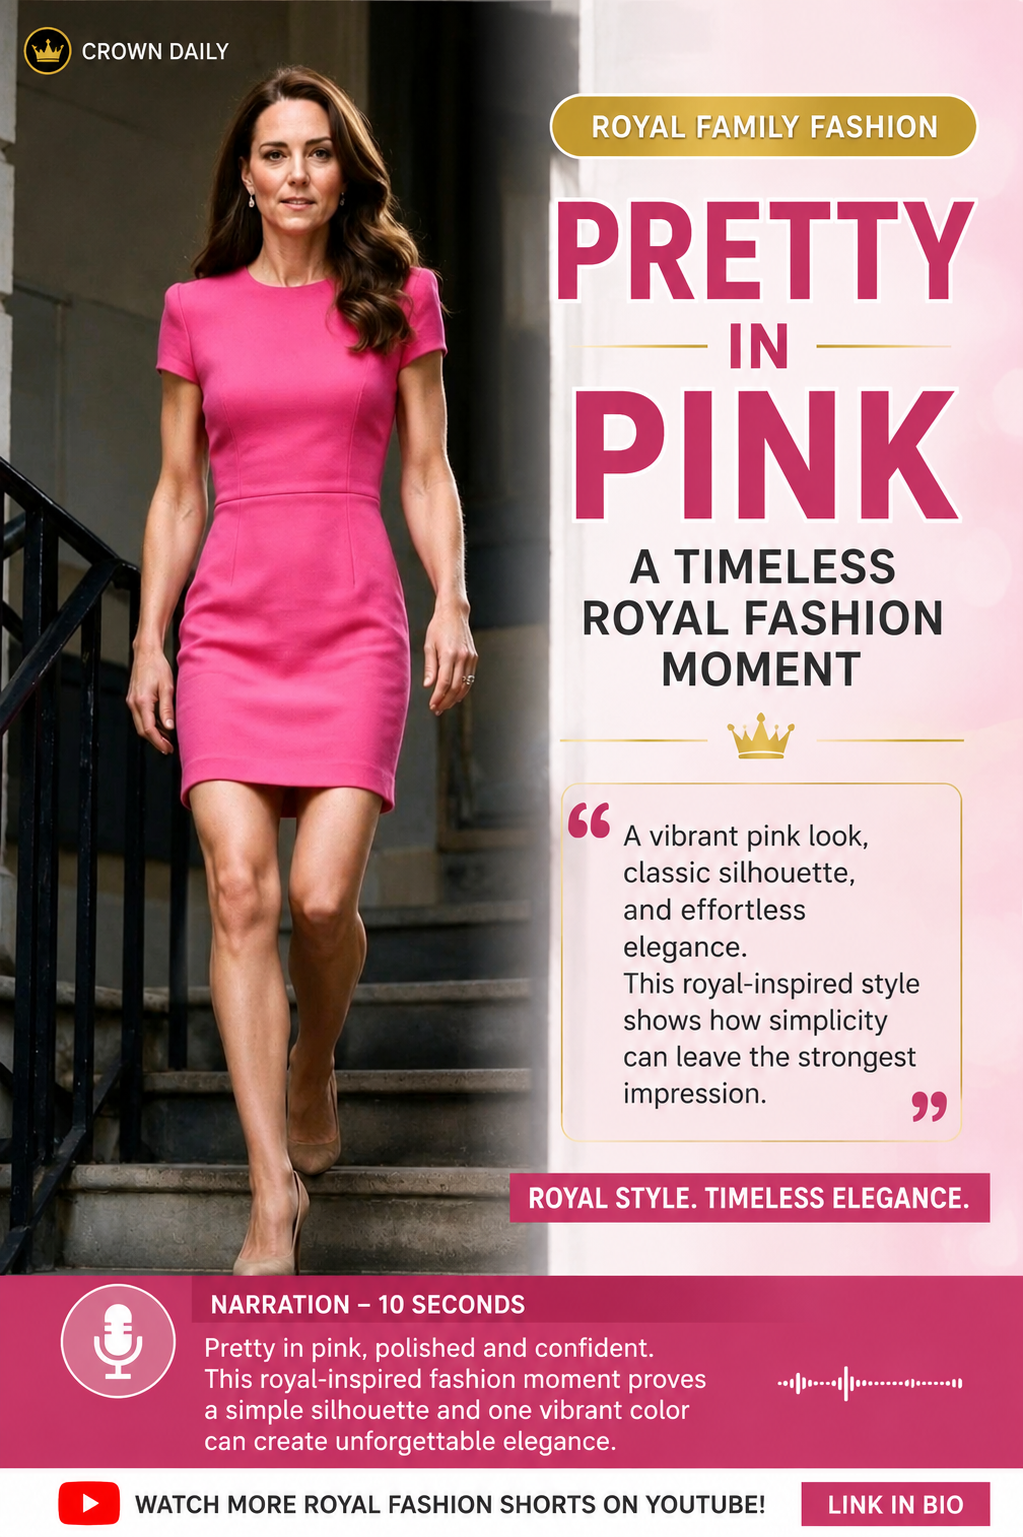
The 10% Royal-Inspired Lesson From the Pink Fashion Photo
The royal-inspired pink fashion image offers a small lifestyle lesson that fits surprisingly well with retirement planning.
The look feels polished because it appears simple and intentional.
One strong color creates the entire statement.
There is no need for endless detail.
That same idea can work beautifully after 50.
A comfortable life does not necessarily require dozens of subscriptions, multiple expensive vehicles, an oversized house, and constant upgrades.
Sometimes elegance comes from choosing what matters and letting go of what no longer adds value.
A well-chosen wardrobe can feel more luxurious than a closet packed with forgotten purchases.
A simpler home can feel more peaceful than a larger property filled with expenses.
And a retirement budget with fewer unnecessary bills can provide something much more valuable than appearances:
freedom.
Try a 30-Day Bill Audit
Before retirement, take one month and review every recurring payment.
Write down:
Bill → Monthly Cost → Annual Cost → Keep / Reduce / Cancel
You may be surprised by the annual numbers.
A seemingly harmless $40 monthly expense equals $480 per year.
A $100 expense equals $1,200.
A $250 bundle of unnecessary services equals $3,000 annually.
When you view recurring expenses annually instead of monthly, financial priorities become much clearer.
Final Thoughts
Preparing for retirement is not only about building the largest possible investment account.
It is also about designing a lifestyle that your retirement income can comfortably support.
Start with your largest recurring expenses.
Review housing.
Look at vehicle payments.
Shop insurance.
Examine your phone and internet plans.
Reduce expensive debt.
Cancel subscriptions you no longer use.
And keep the services that genuinely make your life healthier, easier, or happier.
There is no prize for having the lowest retirement budget.
The goal is to remove expenses that no longer serve you so more of your money remains available for the things that do.
Travel.
Family.
Health.
Hobbies.
Peace of mind.
After 50, one of the smartest financial questions you can ask is surprisingly simple:
“If I stopped working tomorrow, would I still want to pay this bill every month?”
Your answer may help shape a more comfortable retirement.
FAQ
How early should I review monthly expenses before retiring?
Ideally, begin several years before retirement. That gives you time to reduce debt, change housing decisions, compare insurance, and test whether your future retirement budget is realistic.
How much should I try to reduce monthly expenses?
There is no universal target. Even reducing recurring costs by $200 to $500 per month can create meaningful annual savings. Focus first on expenses that provide little value.
Should I cancel all entertainment subscriptions?
No. Retirement should still be enjoyable. Keep the services you regularly use and value. The goal is eliminating waste, not eliminating pleasure.
Is paying off debt more important than investing more?
It depends on the debt interest rate, taxes, liquidity needs, and your financial situation. High-interest consumer debt often deserves serious attention before retirement.
What is the easiest bill to reduce?
Streaming services, mobile plans, internet packages, unused memberships, and forgotten subscriptions are often among the easiest places to start.
Why are fixed expenses so important after retirement?
Because they must be paid whether investment markets are rising or falling. Lower fixed expenses give retirees more flexibility and can reduce pressure on retirement savings.